Selling merch at shows in Germany: the cash box and the one sheet
A cash box and one sheet per night are enough at a German merch table. What is allowed, how the nightly cash report works, and why merch money counts differently from the fee.

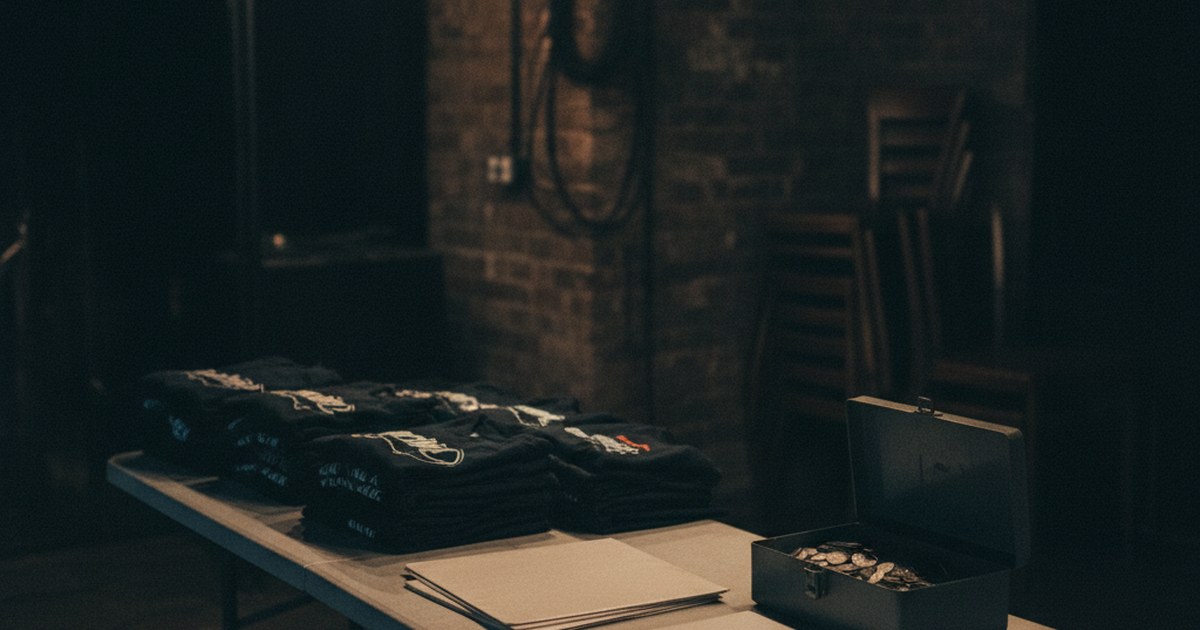
You are selling at shows in Germany — and German cash rules apply at your table, wherever the band is from. The good news fits in one sentence: a cash box and one sheet of paper per night are enough. Selling for cash to many unknown buyers, you may skip recording each sale individually (§ 146 Abs. 1 AO), and Germany's receipt duty — the famous Bon — applies only to electronic till systems (§ 146a AO), which your cash box is not.
The sheet the tax office wants instead is the nightly cash report. It takes four steps.
The night at the table, in four steps
Before doors: count the float
How much change sits in the box? Write the number down before the first customer. Without it, no later calculation comes out right.
During the night: sell, cash into the box
Cash into the box, no individual receipts — the exception covers that. A price sheet on the table belongs there too: prices must be displayed to consumers in Germany, and the sheet spares you questions at the table.
After load-out: write the cash report
Count the final amount, subtract the float: the difference is the night's takings. Date, venue, both numbers and a signature on one sheet — that is the cash report, and it goes into the same binder as every other receipt.
Keep card payments separate
What ran through the card reader shows on the bank statement and is documented there. The cash report carries cash only — mix the two and the count never balances.
Why merch money counts differently from the fee
Performing is freelance, trading is trade — shirt and record sales at any real scale fall on the second side. What that means in full, and where the line runs, is in Taxes for bands in Germany.
For VAT, merch revenue counts into the same pot as everything else: the small-business line applies to the whole band's turnover as a GbR — fees and shirts together, never counted separately.
Where it is honestly unclear
Two questions go to a Steuerberater rather than into this text. From what scale regular selling needs a trade registration depends on frequency and volume — the transitions are fluid, and guessing has no place here: that one goes to the adviser or straight to the tax office. And as soon as you use an electronic till system, receipt and further duties apply — the move from box to app is a bigger step than it looks, and it wants clearing beforehand.
FAQ: Who sells, records and whose money it is
May a friend sell for us?
For the night, yes — who stands at the table is your business. As soon as someone sells regularly and for pay, an employment with its own rules begins; settle that before it becomes a habit.
Do the merch takings go into our records?
Yes — into the spreadsheet and the binder like every other income. The cash report replaces the night's individual receipts, never the bookkeeping: the night's takings from the report become one row in your income-minus-expenses sheet.
Whose money is in the box?
Float and takings belong to the band — the box is the band till. Whoever runs the table counts in before doors and out after load-out; the two numbers on the sheet protect the person at the table.
Venues in Germany
97 in the catalog right now · as of 2026-10-28
- Batschkapp — Frankfurt am Main
- Blue Shell — Köln
- Lido — Berlin (Kreuzberg)
- Lila Eule — Bremen
- SO36 — Berlin (Kreuzberg)
- Sputnikhalle — Münster
- UT Connewitz — Leipzig, Saxony
- Volksbad — Flensburg
Where the next table stands
The table stands where you play. Our open directory lists venues where concerts happen regularly — with website and genre profile, checked and free.
The short version
A cash box and one cash report per night are enough in Germany: float, final count, difference, signature. Prices on the table, card payments kept apart from the cash. Merch at any real scale is trade — and its revenue counts into the whole band's small-business line either way. The two open questions — trade registration and electronic tills — go to the Steuerberater before selling becomes a habit.
Figures as of September 2026, from the sources named below.
Sources
- § 146 Abs. 1 AO (single-recording duty and its exception for cash sales to many unknown buyers; as of September 2026)
- § 146a AO with the BMF FAQ on receipt duty (receipts required only for electronic till systems)
- Preisangabenverordnung (price display towards consumers)
Updated: 2026-09-13
Note
This article provides general information. It is neither tax advice within the meaning of the German Tax Consultancy Act (StBerG) nor legal advice within the meaning of the Legal Services Act (RDG). No individual case is assessed here. For your tax situation please consult a tax adviser (Steuerberater); for legal questions, a lawyer.
Contribution rates, tariffs, levies and deadlines are adjusted regularly. Only the current publications of the competent bodies are authoritative — in particular GEMA, GVL, Künstlersozialkasse, Deutsche Rentenversicherung and the tax authorities. We prepare our content carefully but give no warranty as to accuracy, completeness or currency. Liability for intent and gross negligence, and for injury to life, body or health, remains unaffected.
Last reviewed: 13.09.2026
Read next
The Künstlersozialkasse: half your insurance, if Germany is home
The KSK covers roughly half the social insurance of self-employed artists in Germany. Who gets in, the three-year newcomer rule — and the estimate where sloppiness costs money.
2026-09-07 · Evgeny E.
Split sheets: who owns the song when four people wrote it
One sheet of paper that replaces tomorrow's argument: who holds which share of the song, in writing, before the first release — and what the law decides when the sheet is missing.
2026-09-07 · Evgeny E.
GEMA for musicians: what a band actually pays in Germany
The concert rates, the cost of membership, the reduced newcomer tariff — and when joining pays off. Germany's system, explained for the band standing in it.
2026-09-07 · Evgeny E.
KSK reporting in practice: the annual report, changes, leaving
The annual income report by 1 December, the change notification mid-year, the side job and the clean exit — the KSK routine once you are insured, each report done in minutes.
2026-09-07 · Evgeny E.